Ever wonder how much you’re really paying for auto insurance in Massachusetts? If you’ve ever felt like you’re drowning in insurance jargon and numbers, you’re not alone. In this detailed guide, we’ll unravel everything you need to know about auto insurance costs in the Bay State, from what you’re required to have to how you can save a buck or two.
As you dive into the nitty-gritty of Massachusetts auto insurance, you’ll discover that there’s more to it than just picking a plan and paying premiums. From understanding the essential coverage to getting the best deals on the market, this guide will equip you with the knowledge to make informed decisions, all while keeping your wallet happy.
Understanding Auto Insurance in Massachusetts
Did you know that Massachusetts has some of the most specific auto insurance requirements in the U.S.? It’s not just about having coverage; it’s about having the right kind of coverage.
Whether you’re a seasoned driver or new to the state, understanding these requirements can save you big bucks and keep you legally compliant. Let’s break it down for you.
Basic Requirements for Auto Insurance in Massachusetts
Massachusetts law mandates that every car owner carries certain types of auto insurance. At a minimum, you’ll need to cover bodily injury to others, personal injury protection (PIP), and uninsured motorist coverage. This isn’t optional. If you’re caught without it, expect hefty fines or even a suspended license.
Types of Coverage Available and Their Implications
Sure, meeting the minimum requirements is a must. But, if you want to avoid out-of-pocket expenses after an accident, consider optional coverages like collision and comprehensive. These cover your car regardless of who’s at fault or in cases of theft and natural disasters.
Pro Tip: Comprehensive and collision may not be cheap, but they can save you thousands in repair costs.
Remember, the type of car you drive, your driving history, and even your credit score can affect your premiums. Choose wisely, and you could save a lot on your insurance.
State Laws Influencing Auto Insurance Rates in Massachusetts
Ever wonder why your neighbor pays less for auto insurance? Massachusetts uses a system called “managed competition,” which means different insurers can set rates based on factors like location and driving history. BUT, they can’t use your gender or credit score to determine your rates.
Here’s the deal: State regulations mean insurers need to file their rates and get approval before they can charge you. This helps keep your costs in check, but it also means that shopping around can uncover better deals.
Average Cost of Auto Insurance in Massachusetts
Did you know that the average cost of auto insurance in Massachusetts is lower than the national average? But don’t celebrate just yet—there’s more to the story.
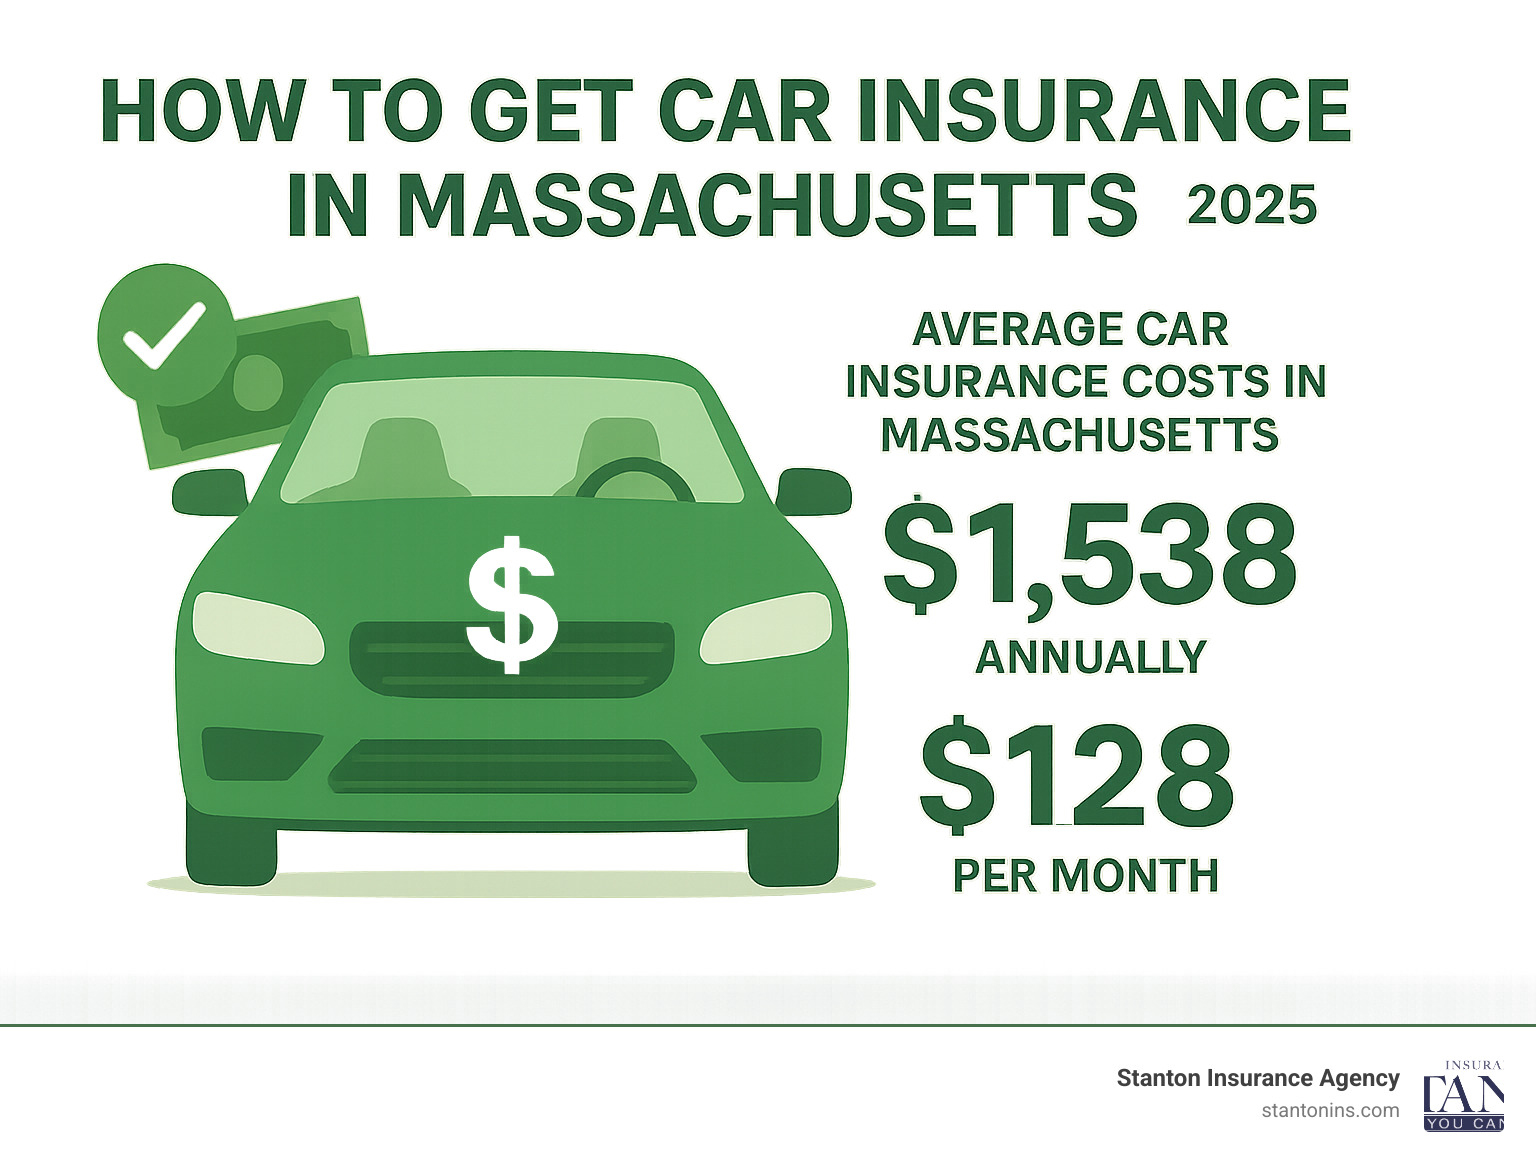
In Massachusetts, drivers typically pay around $1,200 per year for coverage. This figure positions the state as relatively affordable compared to others. But why do these costs vary so widely across the U.S.?
Comparing Auto Insurance Costs Across States
Let’s see how Massachusetts stacks up against other states. Check out the table below.
| State | Average Cost | Minimum Coverage | Full Coverage |
|---|---|---|---|
| Massachusetts | $1,200 | $500 | $1,700 |
| California | $1,800 | $600 | $2,100 |
| Texas | $1,500 | $700 | $2,000 |
| Florida | $2,000 | $800 | $2,500 |
Factors Influencing Insurance Costs in Massachusetts
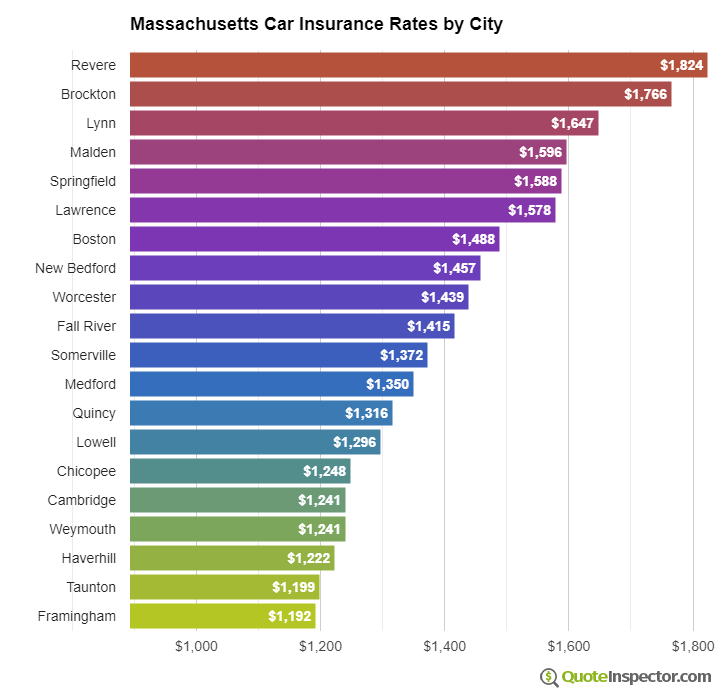
There are several key factors that influence auto insurance costs in Massachusetts. For starters, urban areas like Boston typically have higher rates due to traffic density and accident likelihood. If you’re living in a rural area, you might find cheaper premiums. BUT, don’t forget that your driving record and vehicle type also play a huge role.
Pro Tip: Maintaining a clean driving record can significantly lower your insurance premiums.
Additionally, Massachusetts is a no-fault state. This means your insurance covers your injuries regardless of who caused the accident. Here is the deal: while this can drive up costs, it also provides a safety net for drivers. Always factor in these nuances when comparing rates.
Factors Affecting Auto Insurance Rates
Ever wondered why your auto insurance rates seem to skyrocket? It’s not just random. There are specific factors that insurance companies in Massachusetts consider when setting your rate. Let’s dive into the nitty-gritty.
Insurance is all about assessing risk. The more risk you present, the higher your premium. But what exactly do they look at?
Driving History and Its Impact
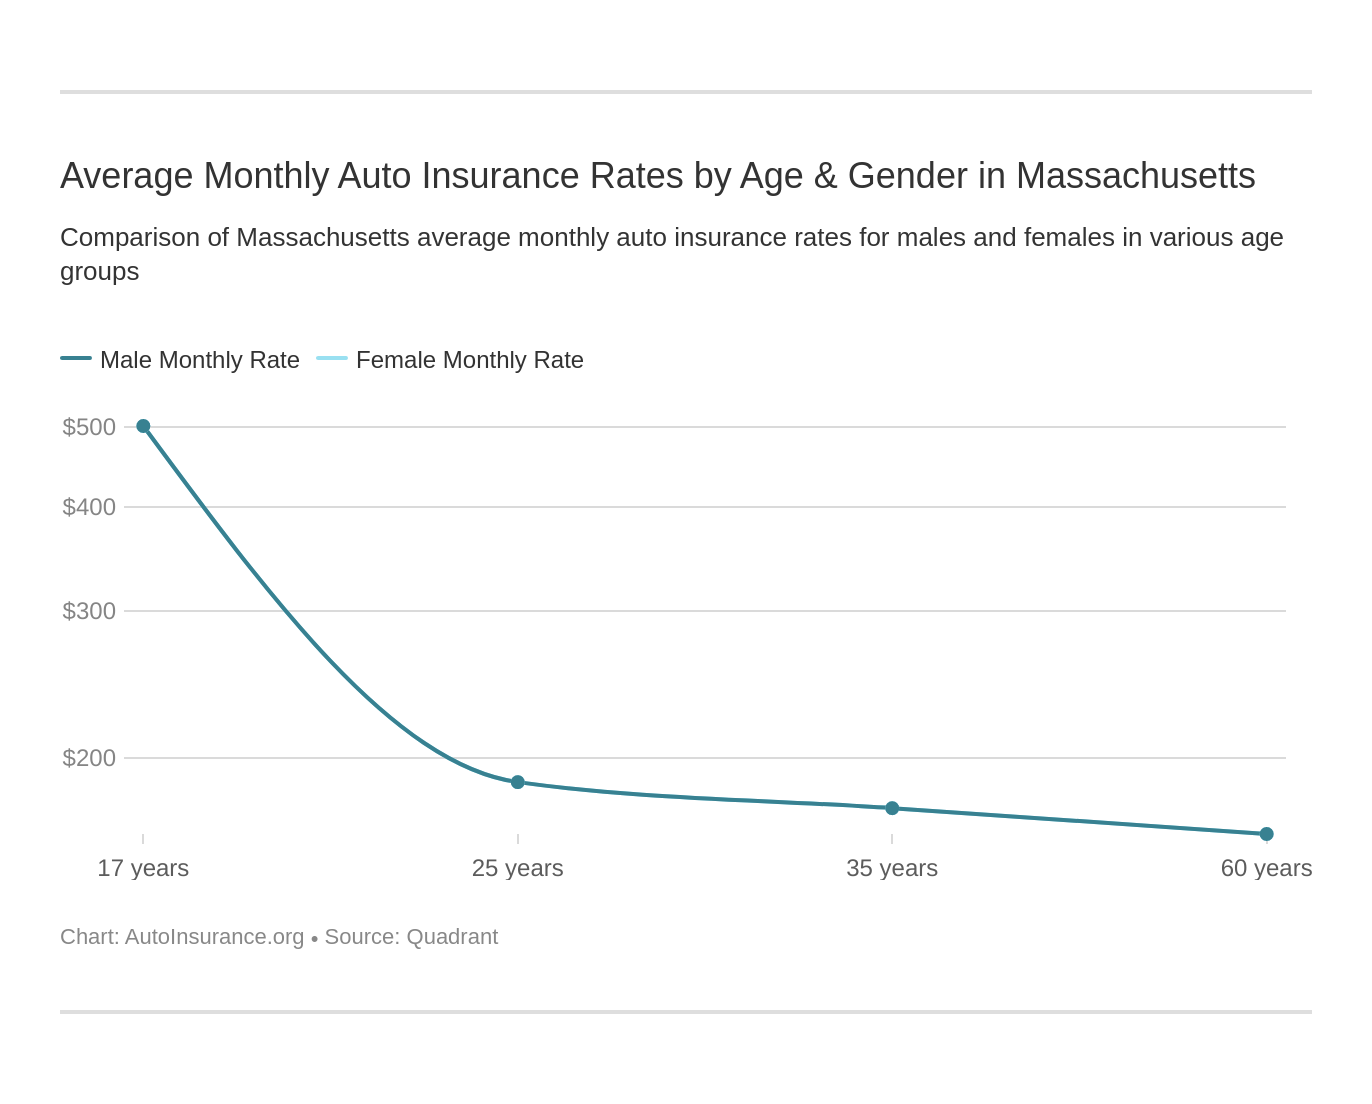
Your driving history is like your report card for the road. If you’ve had accidents, tickets, or even just a few minor fender benders, you might be paying more. Insurance companies see these as red flags. They mean a higher likelihood of future claims, which translates to higher premiums.
But here’s the deal: even if your driving record isn’t spotless, you can still take steps to improve it over time. Safe driving courses, for instance, can potentially reduce your premiums.
Vehicle-Related Factors Affecting Insurance Costs
Your car itself can influence what you pay. Insurers look at several vehicle-related factors to determine your rate. Here are the key ones:
- Make and Model: Some cars are just more expensive to insure. Sports cars often top the list due to their high-performance nature.
- Age of Vehicle: Newer cars may cost more to insure because they’re more expensive to repair or replace.
- Safety Features: Vehicles equipped with advanced safety features might score you some discounts.
- Theft Rate: Some cars are more prone to theft than others. If your model is a frequent target, expect higher rates.
Pro Tip: Want to lower your insurance rate? Consider choosing a car with high safety ratings and low theft rates.
Discounts and Savings Opportunities
Did you know that you could be leaving money on the table when it comes to your auto insurance? In Massachusetts, there are numerous discounts that can significantly reduce your insurance costs.
Here’s the deal: not all drivers are aware of these potential savings. But with a few strategic moves, you can maximize your discounts and keep more cash in your pocket.
Common Auto Insurance Discounts
Massachusetts drivers have access to a variety of discounts. From being a safe driver to bundling policies, let’s explore how you can qualify:
- Safe Driver Discounts: If you maintain a clean driving record, you could see substantial savings. Insurance companies reward cautious drivers.
- Multi-Policy Discounts: Bundle your auto insurance with home or renters insurance to unlock discounts. The more you bundle, the more you save.
- Good Student Discounts: If you’re a student with a B average or better, insurers might offer a discount. Studying pays off, literally!
- Low Mileage Discounts: Drive less, pay less. If your annual mileage is below average, some insurers offer reduced rates.
Steps to Qualify for Discounts
Qualifying for discounts isn’t just about asking for them. You need to take proactive steps:
- Maintain a clean driving record. Avoid accidents and traffic violations.
- Consider bundling your policies. Contact your provider to see what bundles are available.
- For students, focus on keeping your grades up. Submit report cards or transcripts to your insurer.
- Track your annual mileage. If you drive less, report it to your insurer for potential savings.
Maximizing Your Savings Strategy
Now, let’s put it all together. To truly maximize savings, you need a strategy:
Step #1: Regularly review your policy. Insurance needs and discounts can change, so keep your policy updated.
Step #2: Shop around. Different insurers offer different discounts. A little research can go a long way.
Step #3: Leverage technology. Many insurers offer usage-based discounts through apps that monitor your driving habits.
Pro Tip: “Always ask about discounts. Insurers won’t offer unless you ask.”
Remember, every little bit helps. By being proactive, you can unlock substantial savings on your auto insurance in Massachusetts.
Comparing Auto Insurance Providers
Are you overwhelmed by the sheer number of auto insurance options in Massachusetts? You’re not alone. The choices can seem endless, but here’s how you can make sense of it all.
Choosing the right auto insurance provider isn’t just about cost. It’s about finding the balance between price, service, and coverage that meets your needs. Let’s break down the process.
How to Evaluate Auto Insurance Providers
When you’re looking at different providers, start with their financial stability. A company with a strong financial footing is more likely to pay out claims reliably. Next, consider the coverage options they offer. Does it fit your needs, or do you find yourself paying for extras you don’t want?
Customer service is a biggie. How quickly do they respond when you need them? And here’s the deal: How they handle claims can make or break your experience.
Pro Tip: “Look for companies with high customer satisfaction ratings in claim handling.”
Importance of Customer Service and Claims Handling
Imagine getting into an accident, and your insurance company is MIA. Frustrating, right? That’s why customer service and claims handling are crucial. A provider that’s quick to respond and resolves claims efficiently can save you a ton of headaches.
But don’t just take their word for it. Check out reviews and ask friends or family about their experiences. A provider with a solid reputation is invaluable.
Comparison Table: Auto Insurance Providers in Massachusetts
Here’s a quick comparison of some of the top providers in Massachusetts. Look for the balance between cost, customer satisfaction, and special features.
| Provider | Rating | Average Cost | Special Features |
|---|---|---|---|
| Provider A | 4.5/5 | $1,200/year | Accident forgiveness |
| Provider B | 4.0/5 | $1,100/year | Roadside assistance |
| Provider C | 4.2/5 | $1,300/year | New car replacement |
| Provider D | 3.9/5 | $1,150/year | Good driver discounts |
Tips for Reducing Auto Insurance Costs
Did you know that drivers in Massachusetts could save hundreds on their auto insurance with a few strategic moves? Lowering your insurance costs isn’t just about switching providers; it’s about tweaking your strategy.
Here’s the deal: Many drivers don’t realize how much they can cut their premiums by changing simple habits. Whether you’re a new driver or a seasoned pro, these tips can help you keep more money in your pocket.
Bundling Insurance Policies for Maximum Savings
Consider this: bundling your insurance policies could be your ticket to significant savings. Many insurers offer steep discounts when you combine auto insurance with home or renter’s insurance. By sticking with one company for multiple policies, you often earn a “multi-policy” discount. It’s a win-win.
- Reach out to your current provider to inquire about bundling options.
- Compare bundled rates with different insurers to ensure you’re getting the best deal.
Pro Tip: Bundling isn’t just about convenience; it’s a strategic move to slash your insurance costs.
Preventative Measures to Lower Premiums
Think your premium is set in stone? Think again. Implementing preventative measures can significantly reduce your risk profile, leading to lower insurance costs. Safety features like anti-theft devices, advanced braking systems, and fog lights are not just for peace of mind—they can also earn you discounts.
- Invest in safety features for your vehicle.
- Attend defensive driving courses to demonstrate your commitment to safe driving.
By proactively reducing your risk, you make yourself a less costly customer for insurers. And they reward that initiative.
Last Word
In wrapping things up, understanding the nuances of auto insurance in Massachusetts can be a daunting task, but with the right information, you can navigate the complexities and make smarter financial choices. Remember, the goal is not just to find the cheapest option but to strike the perfect balance between cost and coverage. So, stay informed, compare wisely, and drive with peace of mind!
FAQ Section
What are the minimum auto insurance requirements in Massachusetts?
Massachusetts law mandates that drivers carry a minimum amount of liability insurance, including bodily injury, property damage, uninsured motorist protection, and personal injury protection.
How does Massachusetts compare to other states in terms of average auto insurance costs?
Massachusetts tends to have higher average auto insurance costs compared to many other states, largely due to its dense population and high number of drivers.
What factors influence auto insurance rates in Massachusetts?
Several factors can influence rates, including your driving history, age, type of vehicle, and where you live within the state.
Are there discounts available for drivers in Massachusetts?
Yes, many insurance providers offer discounts for safe driving, bundling policies, maintaining a good credit score, and more.
Can bundling insurance policies save me money?
Absolutely! Many insurers offer discounts when you bundle your auto insurance with other policies like home or renters insurance.

